Boat Balloon Payment Calculator – Lower Monthly Payments, Lump Sum at the End
Calculate Your Boat Balloon Payment Loan
See your lower monthly payment, the balloon due at the end, and the true total cost — before you sign.
- Balloon Payment Due (end of term): $0.00
- Loan Amount: $0.00
- Standard Monthly Payment (no balloon): $0.00
- Monthly Savings vs Standard Loan: $0.00
- Total Interest Paid: $0.00
- Total Cost (Payments + Balloon): $0.00
- Extra Interest vs Standard Loan: $0.00
| Year | Principal Paid | Interest Paid | Remaining Balance |
|---|
At the end of the term, the remaining balance — your balloon payment of $0.00 — is due in full. Plan to refinance it, sell the boat, or pay it from savings.
A balloon payment loan lets you buy the boat you want with a much smaller monthly payment — in exchange for one large lump-sum payment at the end of the term. This free boat balloon payment calculator shows your monthly payment, the balloon amount due, and the true total cost, so you can decide whether the trade-off is worth it. For the full explainer — when balloon loans make sense and when they don't — see our guide to boat loan balloon payments.
How to Use the Boat Balloon Payment Calculator
- Enter the boat price — the purchase price of the boat.
- Enter your down payment — 10 to 20 percent is typical.
- Enter the APR and loan term — balloon loans usually run 5 to 7 years.
- Set the balloon percentage — the lump sum due at the end, as a percentage of the loan amount. 20 to 40 percent is common.
- Toggle $/£ — the calculator works in USD or GBP.
How a Boat Balloon Payment Loan Works
With a standard boat loan, your monthly payments pay the loan off completely by the end of the term. With a balloon loan, part of the balance is deferred: you pay less every month, but a large lump sum — the balloon — is still owed when the term ends. The monthly payment is calculated on the loan minus the present value of that future balloon payment, which is why it drops so much.
For example, a $60,000 boat with $12,000 down (20%) at 7.5% APR over 7 years costs about $736 a month on a standard loan. Add a 30% balloon ($14,400) and the payment falls to about $605 a month — roughly $131 less every month. The catch: you still owe that $14,400 at the end, and you pay about $3,407 more interest overall. The calculator above shows both sides of the deal for your numbers.
When Does a Balloon Payment Make Sense?
Balloon loans work best when you have a clear plan for the final payment: you expect to sell the boat before the term ends, refinance the balloon into a new loan, or you know a bonus or savings will cover it. They are popular with buyers who upgrade boats every few years — the lower payment fits the budget now, and the sale covers the balloon later.
They are risky when there is no exit plan. If the boat's value falls below the balloon amount, or refinancing is not available when the term ends, you can be stuck. Never take a balloon loan hoping rates will fall — model the standard loan alongside it with our boat loan comparison calculator and our boat loan calculator before you sign. If a balloon deal is the only way the boat fits your budget, check our boat affordability calculator first — a cheaper boat on a standard loan is often the safer buy.
What Happens When the Balloon Payment Is Due?
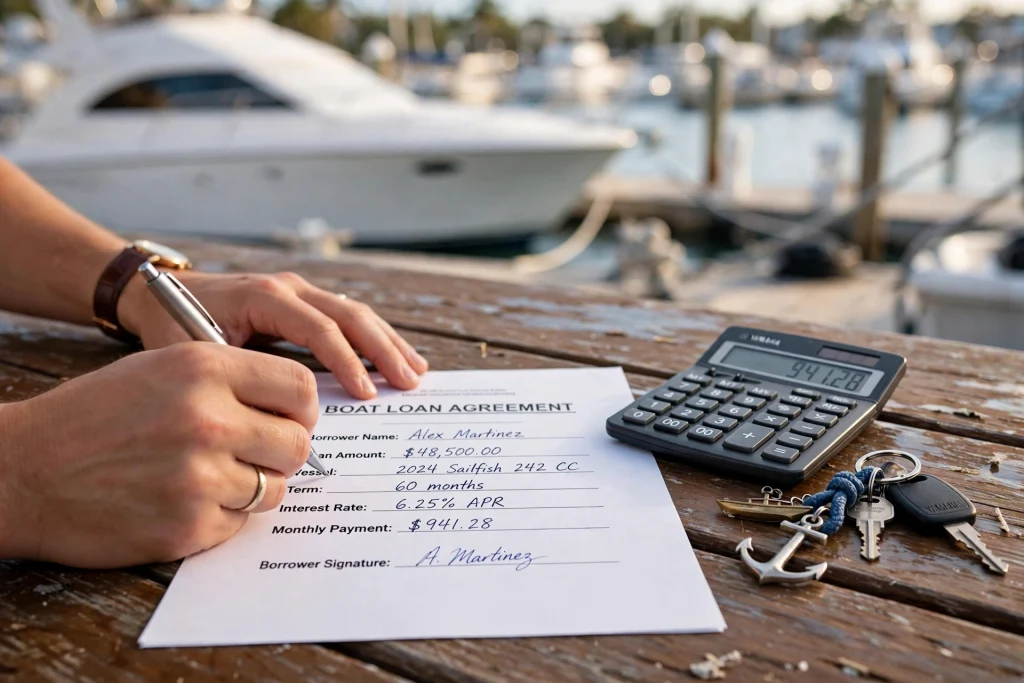
Three options, and you should know which one you will use before signing: pay the lump sum from savings, refinance the balloon into a new loan (subject to rates and the boat's value at the time), or sell the boat and use the proceeds to settle it. Most balloon borrowers plan on the second or third option. Whatever you choose, keep the balloon date on your calendar from day one — it is easy to forget a payment seven years away.
Boat Balloon Payment Calculator FAQs
How much lower is the payment with a balloon loan?
It depends on the balloon size. A 30% balloon typically cuts the monthly payment by 15–20% versus a standard loan of the same term. Enter your figures above for the exact number.
Is a balloon payment loan a good idea for a boat?
It can be, if you have a solid plan for the final lump sum — a planned sale, a refinance, or savings set aside. Without a plan, the lower payment is a trap: you pay more interest overall and still owe a large sum at the end.
What happens if I can't pay the balloon payment?
You will usually need to refinance the remaining balance or sell the boat. If neither is possible, the lender can repossess the boat — so never sign a balloon loan without an exit plan.
What is a typical balloon payment percentage for boats?
Most marine balloon loans set the balloon at 20–40% of the loan amount. Higher balloons mean lower monthly payments but a bigger final bill.
Can I refinance a balloon payment?
Yes — most marine lenders will refinance a balloon balance into a new loan, provided the boat still holds enough value and your credit is in good shape. Compare the cost with our boat refinance calculator.
Do balloon loans cost more overall?
Almost always. You pay interest on a larger balance for longer, so total interest is higher than a standard loan. The calculator shows the extra interest figure so you can judge the trade-off honestly.
Related Boat Loan Calculators
- Boat Loan Calculator — monthly payments and ownership costs for any boat.
- Boat Loan Comparison Calculator — compare up to 3 loan offers side-by-side.
- Boat Refinance Calculator — monthly savings and break-even on a refinance.
- Boat Affordability Calculator — work backwards from your budget to your max boat price.
- Boat Down Payment Calculator — see how your down payment changes the loan.
- Boat Loan Amortization Schedule — every monthly payment split into principal and interest.
- All boat loan calculators — the full toolkit in one place.

Michael Carter is a financial research writer specializing in vehicle financing, loan calculations, interest rates, and consumer budgeting. He creates practical, easy-to-understand resources that help readers make more informed financing decisions.