How to Finance a Sailboat: Loans, Rates and Requirements
Financing a sailboat is different from financing a powerboat. Lenders look closely at the hull, the rigging, and whether the boat can serve as a second home. If you know how to finance a sailboat before you start shopping, you can avoid the two most common mistakes: falling in love with a boat no lender will touch, and accepting the first rate a dealer offers. This guide covers the loan types, the credit and down payment lenders expect, the survey, the paperwork, and the tax break many buyers miss.
How to finance a sailboat with a marine loan
The most common route is a secured marine loan, which works much like a car loan. The lender holds a lien on the sailboat, and if you stop paying, the lender can repossess it. Because the boat backs the debt, terms beat unsecured borrowing: repayment periods typically run 10 to 20 years, fixed rates are the norm, and most lenders ask for 10 to 20 percent down.
Most marine lenders set a minimum loan amount, often around $25,000. A used daysailer or small trailer sailer can cost less than that, so if your purchase is under the minimum, a marine loan may not be available. In that case a personal loan is the realistic route; see our boat loan vs personal loan comparison. Rates depend heavily on your credit: as of late 2025, the average boat loan rate sat around 8.88 percent, with borrowers above 740 averaging 8.73 percent and fair-credit borrowers paying nearer 9.85 percent. Our guide to how to get the best boat loan rate explains how to shop lenders against each other; check current boat loan interest rates before you apply.
What credit score do you need?
Marine lenders generally require a minimum FICO score in the 650 to 680 range, though some specialty lenders work with scores as low as 600. Below 600, traditional boat financing is largely unavailable. Your score shapes every term, not just approval. Scores of 760 and above get the best terms, with rates in the 6 to 7.5 percent range on new boats. Scores of 700 to 759 still qualify for competitive rates. Scores of 650 to 699 pay 1.5 to 3 percent more and may need a larger down payment. Before you apply, pull your credit reports and dispute errors: a 30-point improvement can save thousands over a 15-year loan.
How much down payment will you need?
Plan on 10 to 20 percent down for a new sailboat. Used boats change the math: lenders typically finance 75 to 85 percent of the value on a boat 1 to 5 years old, 70 to 80 percent on one 6 to 15 years old, and 60 to 75 percent on one 16 to 25 years old. So an older boat needs 20 to 40 percent down, and the survey becomes mandatory.
Lenders finance a percentage of the purchase price or the appraised value, whichever is lower. If you agree to pay $200,000 but the lender values the boat at $180,000 and offers 80 percent, your loan tops out at $144,000, so you need $56,000 cash at closing, not $40,000. Run the numbers first with our boat loan APR calculator.
The marine survey: the step sailboat buyers cannot skip
For a used sailboat, most lenders require a professional marine survey by a certified inspector before funding the loan. The surveyor examines the hull, rigging, engine, and systems, then assigns a fair market value. Survey fees typically run $25 to $35 per foot, so expect roughly $900 to $1,400 for a 35-foot sailboat, paid out of pocket before closing.
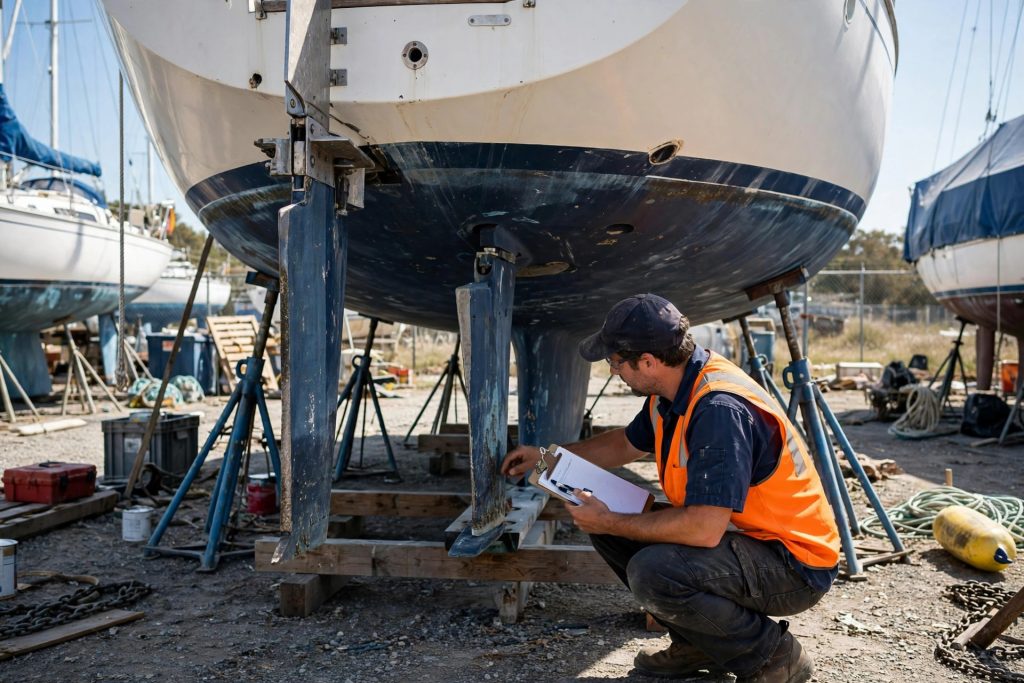
If the survey value comes back below the purchase price, the lender may cut the loan amount or require a larger down payment. If it finds serious problems, such as osmosis in the hull or worn standing rigging, the lender can refuse the loan or hold money in escrow until the work is done. Build a survey contingency into your purchase agreement so you can renegotiate or walk away.
Coast Guard documentation vs state registration
Every recreational boat in the US needs either state registration or federal documentation through the US Coast Guard. Federal documentation is available to vessels of at least five net tons wholly owned by a US citizen, and most sailboats over about 25 feet qualify. It creates a federal ownership record and lets the lender file a preferred ship mortgage, a lien with priority over most other claims. That is why many marine lenders require documentation for larger loans. Ask your lender early, because it shapes your closing timeline.
The second-home tax break many buyers miss
Under federal tax law, a boat counts as a qualified residence if it has sleeping, cooking, and toilet facilities. If your sailboat meets that description and the loan is secured by the vessel, you can deduct the interest just as you would mortgage interest on a house, as the IRS states in Publication 936.
The deduction applies to acquisition debt up to $750,000 across all your qualified residences combined, or $375,000 if married filing separately, and you must itemize to claim it. Two caveats: an unsecured personal loan does not qualify, and a home equity loan secures the debt against your house, not the boat. If you plan to live aboard, read our guide on how to finance a liveaboard boat, because some lenders treat full-time liveaboard use differently.
What lenders ask for, and how long it takes
Expect two years of federal tax returns with all schedules, W-2 or 1099 forms, and pay stubs covering at least 30 days. A personal financial statement lets the lender calculate your debt-to-income ratio, which most lenders want under 40 to 45 percent including the new boat payment. On the vessel side, the lender needs the year, make, and model, the 12-character Hull Identification Number, and a copy of the purchase agreement.
A boat loan runs about two to five weeks from pre-approval to closing: one to five days for pre-approval, 5 to 15 days for underwriting, and one to five days to close. Shop for boats and lenders at the same time, and get pre-approvals from at least three lenders before you accept a dealer quote.
The real cost goes beyond the monthly payment
Lenders require hull insurance covering the full loan amount, with the lender listed as loss payee, and will not disburse funds without a bound policy. Shop for marine insurance before you close. Then budget for the costs the loan payment does not cover. The widely cited rule of thumb is to set aside roughly 10 percent of the boat’s value each year for maintenance and upkeep: bottom paint, rigging inspections, engine service, sail repairs, and electronics. Marina slip fees, winter storage, and haul-out costs sit on top of that number. A buyer who checks only the monthly payment is setting themselves up for trouble. The real question is whether you can afford the payment plus the carrying costs, every year, for as long as you own the boat.
Financing a sailboat rewards preparation: check your credit, save a realistic down payment, budget for the survey, and get pre-approved by more than one lender.

Michael Carter is a financial research writer specializing in vehicle financing, loan calculations, interest rates, and consumer budgeting. He creates practical, easy-to-understand resources that help readers make more informed financing decisions.