Refinancing a Boat Loan: How to Lower Your Financing Costs
Refinance a boat loan when your current financing is costing more than it should. A high APR, expensive monthly payment, or long remaining term can add thousands to your total borrowing cost and make your boat harder to afford. If your credit has improved or better rates are available, refinancing can replace the existing loan with terms that better fit your budget.
The key is to compare your current loan balance, APR, monthly payment, remaining term, refinance fees, and total interest against a new offer using our boat refinance calculator. This shows whether refinancing will actually save money rather than simply lower the monthly payment..
The key is not simply finding a lower monthly payment. Compare your current loan balance, APR, remaining term, new refinance rate, fees, and total interest. This shows whether replacing the existing loan will actually reduce your financing cost or only spread the debt over a longer period.
What Does It Mean to Refinance a Boat Loan?
Refinancing a boat loan means replacing your existing boat financing with a new loan, usually from a different lender, to change the interest rate, repayment term, monthly payment, or overall borrowing cost.
The new lender uses the refinance loan to pay off the existing balance. You then make payments under the new loan agreement.
For example, if you currently owe $45,000 at 10% APR and qualify for a new loan at 7.5%, refinancing could reduce the interest charged on the remaining balance. However, the actual savings depend on the new term and any fees associated with the refinance.
When Does Refinancing a Boat Loan Make Sense?
Refinancing can make sense when the new loan improves your overall financing position. Common situations include:
- Your credit score has improved: A stronger credit profile may help you qualify for a lower APR.
- Current rates are lower: A lower market rate can create an opportunity to replace expensive financing.
- Your monthly payment is too high: Extending the remaining term may reduce the monthly obligation, although it can increase total interest.
- You want to repay the boat sooner: A lower rate combined with a shorter term may help reduce long-term interest.
- Your current loan has unfavorable terms: Refinancing can provide different repayment conditions.
Your credit profile, income, debt-to-income ratio, loan-to-value ratio, boat age, vessel value, and lender requirements can all affect the refinance offer.
How Can You Tell If Boat Loan Refinancing Will Save Money?
Compare your current remaining loan cost with the new refinance loan cost, including all refinancing fees.
For example, if refinancing reduces your payment by $80 per month and the new loan costs $800 in fees, the approximate break-even period is:
$800 ÷ $80 = 10 months
After about 10 months, the monthly savings begin to offset the refinancing costs.
Also compare:
- Current loan balance
- Current APR
- New APR
- Remaining term
- New loan term
- Monthly payment
- Total remaining interest
- Refinance fees
- Prepayment penalties
A refinance is more attractive when the total savings after fees are meaningful and the new repayment term does not unnecessarily extend the debt.
For a quick payment comparison, use the boat loan calculator to test different APRs, loan balances, and repayment terms.
How Does Your Credit Score Affect Boat Loan Refinancing?
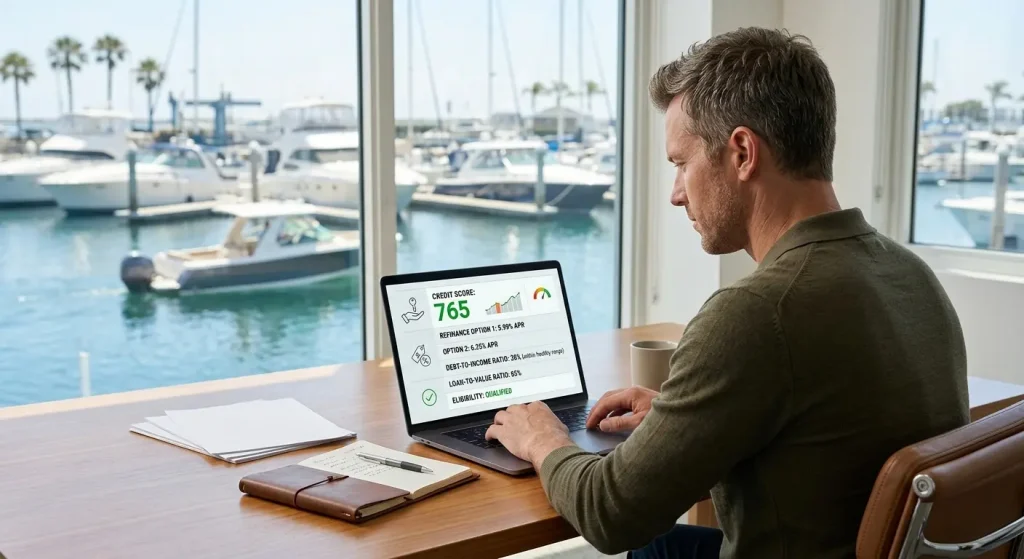
Your credit score can influence the APR, loan terms, and lender options available when refinancing a boat loan. A stronger credit profile may qualify you for more competitive financing, which can reduce interest costs over the remaining loan term.
If your credit score has improved since you originally financed the boat, compare new offers against your existing APR. Even a modest rate reduction can produce meaningful savings when a substantial balance remains.
Lenders may also evaluate your income, debt-to-income ratio, payment history, loan-to-value ratio, and boat value when reviewing a refinance application.
Check your credit and current debt position before applying. For qualification factors, see credit score requirements for a boat loan.
What Costs Should You Check Before Refinancing?
A lower APR does not automatically guarantee savings. Check every cost connected with replacing the existing loan.
Review these costs:
- Refinance or origination fees
- Title or registration charges
- Documentation fees
- Prepayment penalties on the existing loan
- Required insurance
- Appraisal or valuation costs, if applicable
- Total interest under the new loan
Also check whether the existing lender charges a fee for paying the loan early. A penalty can reduce or eliminate the benefit of a lower interest rate.
Should You Lower Your Payment or Pay Off the Boat Faster?
The best refinance structure depends on your financial objective.
Choose a lower monthly payment when improving monthly cash flow is the priority. A longer repayment term can reduce the payment, but it may increase total interest.
Choose a shorter repayment term when reducing total interest is more important. The monthly payment may increase, but the balance is paid down faster.
Choose a lower APR with a similar term when the goal is straightforward interest savings without significantly changing the repayment schedule.
Compare these options before accepting a refinance offer rather than choosing based only on the advertised monthly payment.
How Do You Compare Boat Loan Refinance Offers?
Request offers using the same loan balance and compare them side by side.
Focus on:
- APR — the annual cost of borrowing.
- Monthly payment — the required periodic payment.
- Remaining term — how long you will continue making payments.
- Total interest — the financing cost over the new loan.
- Fees — costs added to the refinance.
- Prepayment terms — whether you can repay early without penalties.
- Loan-to-value requirements — how the boat’s value compares with the amount financed.
A lower APR is useful only when the complete refinance structure produces a meaningful improvement.
What Should You Do Before Applying to Refinance a Boat Loan?
Start with your current loan statement. Record the outstanding balance, APR, monthly payment, remaining term, and any early-payoff fee.
Then compare refinance offers using the same loan balance and repayment period. Check lender eligibility requirements and confirm whether your boat meets applicable age, value, registration, and collateral requirements.
Finally, compare the total remaining cost of your current loan with the total cost of the refinance, including fees. If the savings remain positive after fees and the new terms fit your budget, refinancing may reduce your boat financing costs.
Before contacting a lender, run several rate and term scenarios with the boat loan calculator so you have a realistic payment and total-interest benchmark.
FAQs
Can you refinance a boat loan?
Yes. Refinancing a boat loan means replacing your existing boat financing with a new loan, usually to secure a lower APR, reduce the monthly payment, change the repayment term, or reduce the total interest cost.
Is it worth refinancing a boat loan?
Refinancing can be worthwhile when the new loan provides meaningful savings after accounting for refinance fees and any prepayment penalty. Compare your current APR, remaining balance, remaining term, new APR, fees, and total interest before switching.
When should I refinance my boat loan?
Consider refinancing when your credit score has improved, available interest rates have fallen, or your current loan has an unfavorable APR or repayment structure. The more balance and term remaining, the greater the potential impact of a lower rate.
Can refinancing lower my boat loan payment?
Yes. A lower APR can reduce the monthly payment, while extending the repayment term can reduce it further. However, a longer term may increase the total interest paid, so compare the monthly payment with the total loan cost.
How much can I save by refinancing a boat loan?
Your potential savings depend on the remaining loan balance, current APR, new APR, remaining term, new term, and refinancing fees. Compare the total cost of both loans rather than judging savings from the monthly payment alone.

Michael Carter is a financial research writer specializing in vehicle financing, loan calculations, interest rates, and consumer budgeting. He creates practical, easy-to-understand resources that help readers make more informed financing decisions.