Are boat loans simple interest?
Yes. The vast majority of boat loans are simple interest loans. Interest is calculated daily on your outstanding principal balance only, so a $25,000 loan at 7% accrues about $4.80 in interest per day. Because of this, every extra payment you make goes straight toward reducing your principal and the total interest you will pay.
What Does Simple Interest Mean on a Boat Loan?
Simple interest means the lender charges interest only on the money you still owe, never on previously accrued interest. The daily calculation is straightforward: (current principal balance x annual interest rate) / 365. As one marine lender puts it, simple interest is assessed by multiplying the account’s current principal amount, and only the principal, by the interest rate.
Take a real example: a $25,000 boat loan at 7% accrues ($25,000 x 0.07) / 365, which is $1,750 / 365, or about $4.80 per day. Pay the loan down to $20,000 and the daily interest drops to about $3.84, automatically, without you changing a thing. There is no compounding, so unpaid interest is never added to your balance to earn more interest the way a credit card balance works.
How Does Simple Interest Affect Your Monthly Payment?
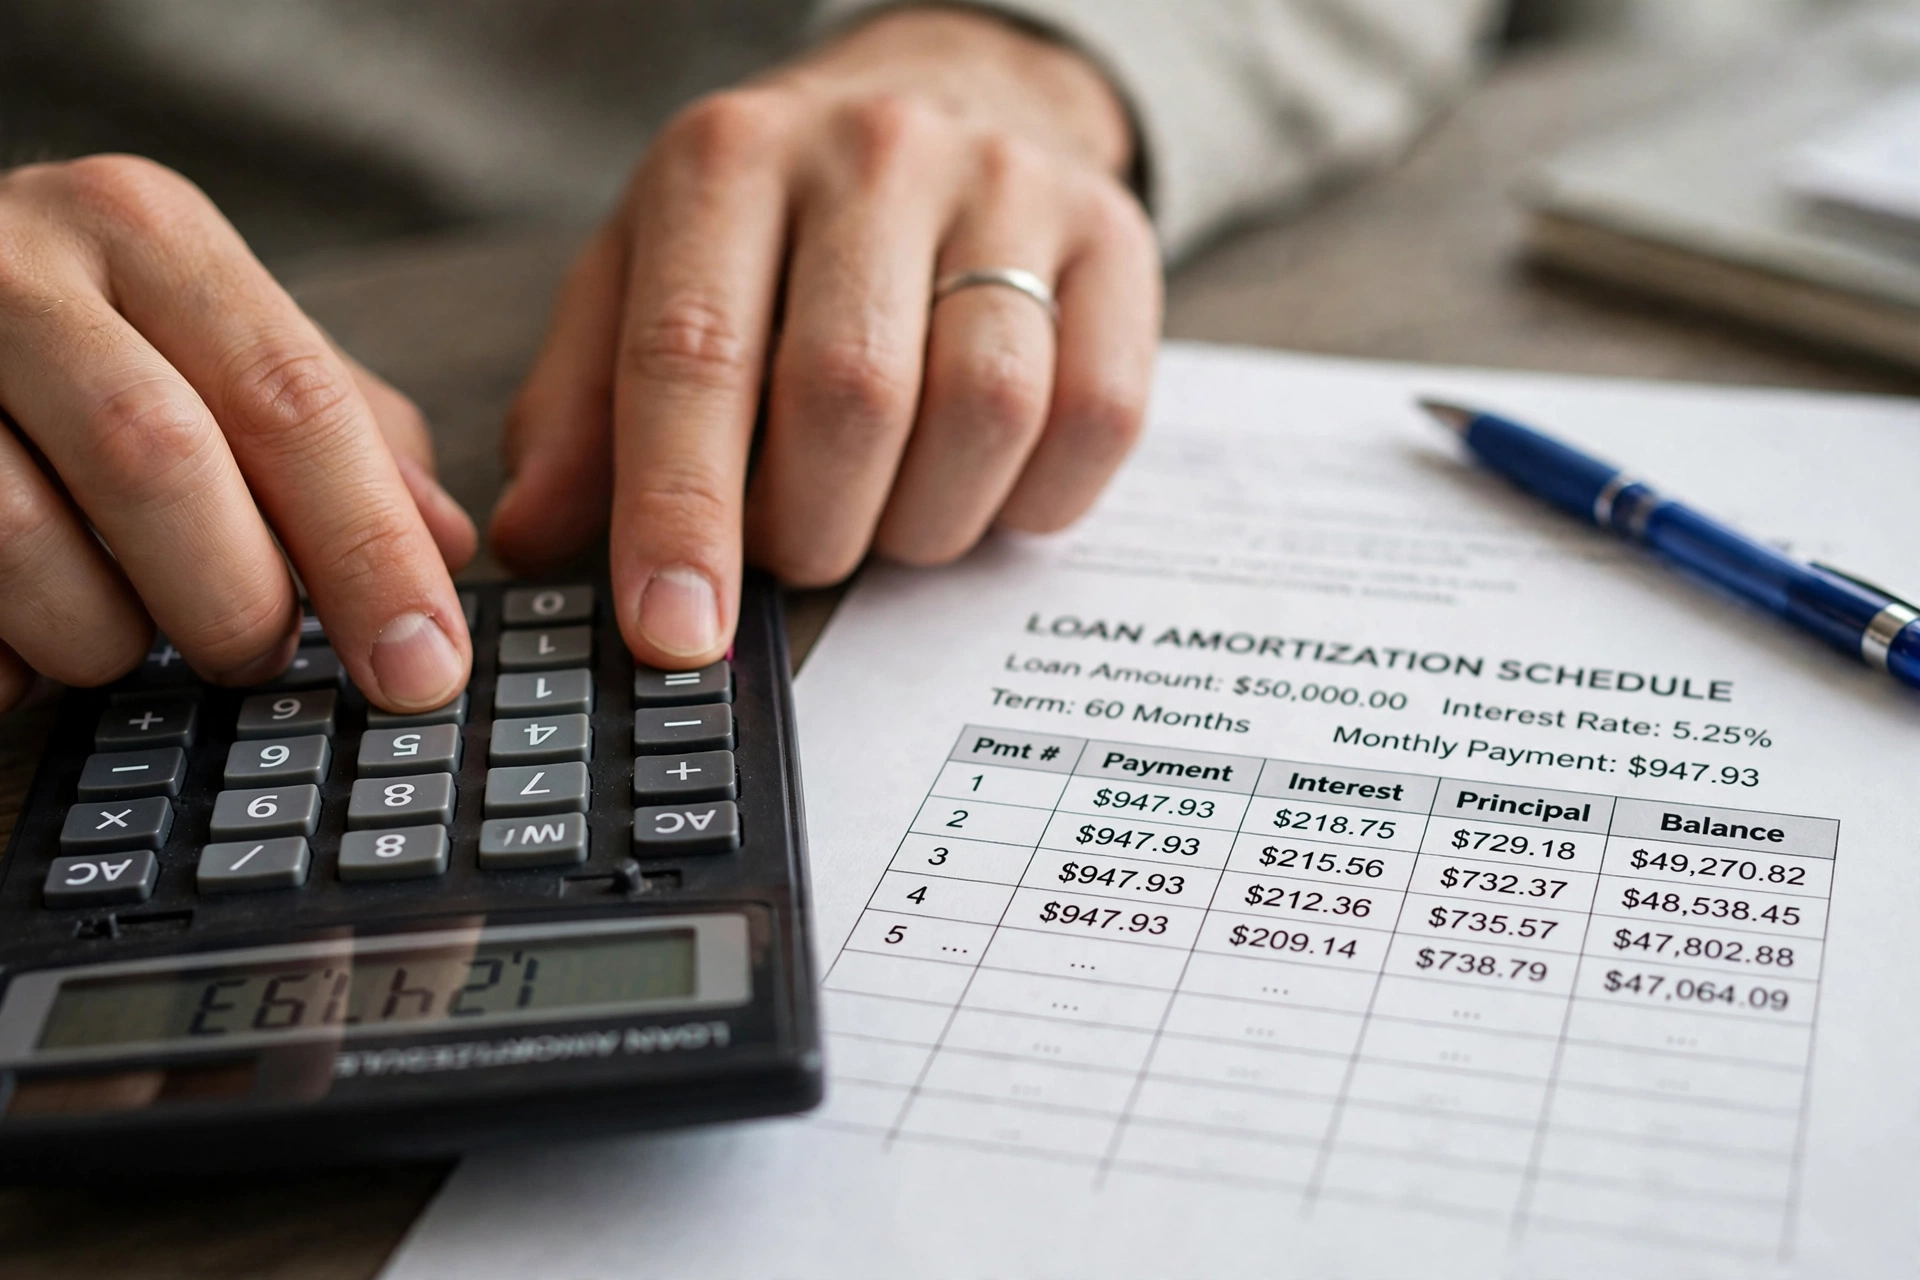
Your payment is set by the standard amortisation formula, so it stays the same each month, but the split between interest and principal shifts over time. In the early years, most of each payment covers the interest that has accrued; later, more of it reduces your principal. You can see this month-by-month split on a boat loan amortisation schedule.
Here is what it looks like with real numbers. A $50,000 boat loan at 8% over 10 years costs about $607 a month and roughly $22,800 in total interest. On day one, interest accrues at ($50,000 x 0.08) / 365, about $10.96 per day. Five years in, once the balance is much lower, that daily figure is far smaller, even though the rate never changed. Run your own figures through our boat loan calculator to see how the balance falls for your loan amount and term.
Are All Boat Loans Simple Interest?
Nearly all modern marine lenders and credit unions write their boat loans as simple interest instalment loans, and many state this explicitly in their loan disclosures. The interest type is separate from the rate type: most boat loans carry a fixed interest rate, so your monthly payment never changes, and the interest is still calculated on the simple basis described above. Compare typical figures on our boat loan interest rates page.
The exception is precomputed interest, sometimes called the Rule of 78s, where the lender fixes your total interest upfront and early payoff saves you very little. This was once common in some types of consumer lending but is rare in marine lending today. Still, it costs nothing to confirm: before you sign, ask the lender directly, “Is this a simple interest loan?” and check that the answer matches the promissory note and the Truth in Lending disclosure.
How Can You Tell What Kind of Interest Your Boat Loan Charges?
Read the loan agreement before you sign and look for the words “simple interest” or language about interest being calculated daily on the outstanding balance. The Truth in Lending disclosure that accompanies most consumer loans will also spell out how interest accrues. If a lender cannot answer the question plainly, treat that as a warning sign and compare offers elsewhere.
Also check for prepayment penalties. With a simple interest loan, extra payments always save you interest, because each extra payment reduces the balance that tomorrow’s interest is calculated on. That is why paying off a boat loan early is such a powerful move on a simple interest loan: every pound of principal you retire early is a pound that stops accruing daily interest.
Frequently Asked Questions
Are most boat loans simple interest?
Yes. Nearly all modern marine lenders and credit unions write boat loans as simple interest instalment loans. Interest accrues daily on your outstanding principal only, so paying extra or paying early reduces the total interest you will pay.
How is simple interest calculated on a boat loan?
Multiply the current principal balance by the annual interest rate and divide by 365. On a $25,000 balance at 7%, that is ($25,000 x 0.07) / 365, or about $4.80 of interest per day. As you pay the balance down, the daily amount shrinks.
Does making extra payments on a simple interest boat loan save money?
Yes. Because interest is charged only on the remaining balance, any extra payment reduces the principal immediately, which means less interest accrues from that day forward. Use our boat loan calculator to compare your payoff with and without extra payments.
Can boat loans use precomputed interest instead?
It is rare today, but a few lenders still use precomputed interest (the Rule of 78s), where your total interest is fixed upfront and early payoff saves very little. Always confirm in writing that your loan is simple interest before you sign.

Michael Carter is a financial research writer specializing in vehicle financing, loan calculations, interest rates, and consumer budgeting. He creates practical, easy-to-understand resources that help readers make more informed financing decisions.