Is it easier to finance a new or used boat?
Yes, a new boat is easier to finance than a used boat. Lenders offer new boats lower interest rates, longer repayment terms and simpler approval, because a new boat has a known value, a manufacturer warranty and no hidden wear. A used boat can still be financed, but expect a higher rate, a shorter term and a marine survey first.
Why is a new boat easier to finance?
Lenders like certainty, and a new boat gives them plenty of it. The value is easy to establish from the manufacturer’s price list, the boat comes with a warranty, and there is no service history to worry about. That lower risk shows up in three ways that directly help the borrower.
Lower interest rates. New boats usually qualify for the lowest rates a marine lender offers. The lender knows exactly what the boat is worth and that it is in perfect condition, so the risk of the loan going bad is lower. Used boats, by contrast, are priced at higher rates to reflect the extra risk of age, wear and uncertain value.
Longer loan terms. A new boat can often be financed over 15 to 20 years, which spreads the cost and keeps the monthly payment down. Lenders cap used-boat terms much sooner, because the boat must still be worth something at the end of the loan. A shorter term means a higher monthly payment on the same loan amount.
Simpler approval. Financing a new boat through a dealer is often a smooth, standardised process. The dealer works with marine lenders every day, the paperwork is familiar, and there is no survey to arrange. Approval can be quick when your credit and income check out. For the latest rate picture, see our guide to current boat loan interest rates.
What makes a used boat harder to finance?
None of this means a used boat cannot be financed. It means the lender works harder to protect itself, and that extra caution lands on the borrower in four ways.
Age limits. Most marine lenders set a maximum age for the boat at the end of the loan, often around 20 years, and some will not finance boats older than 10 to 15 years at all. An older boat can be refused outright, however good its condition. Our guide explains how old a boat can be to finance in detail.
Higher interest rates. A used boat loan typically carries a rate one to two percentage points above a comparable new-boat loan. The lender is pricing in the risk that the boat’s value falls faster than the loan balance.
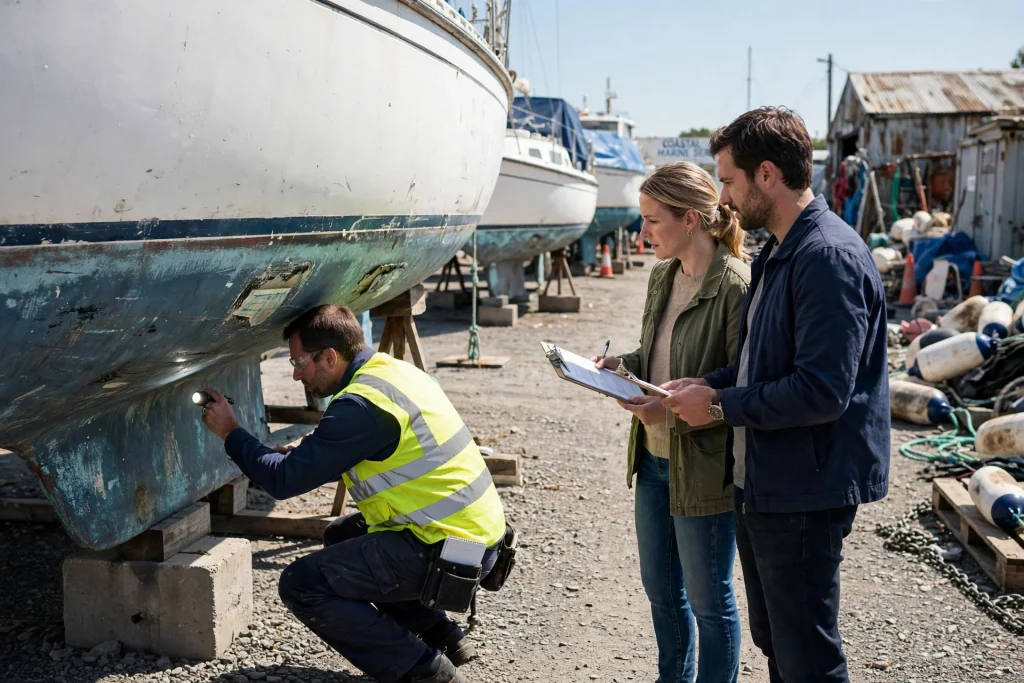
A marine survey is usually required. Before approving a used-boat loan, most lenders ask for an independent marine survey to confirm the boat’s condition and market value. The survey costs the buyer money and time, and a poor survey can reduce the amount the lender will offer or stop the loan entirely.
Shorter terms and bigger deposits. Lenders often shorten the term on a used boat and ask for a larger deposit, typically 20% or more, to keep the loan-to-value ratio safe. Both push the monthly payment up. If approval feels like a struggle, read our answer to are boat loans hard to get for the factors lenders weigh most.
New vs used: what the numbers look like
Take a $50,000 boat as an example. Finance it new at 7.5% over 15 years and the monthly payment is about $464. Finance the same $50,000 as a used boat at 9% over 10 years, a typical used-boat term, and the payment is about $633 a month. That is roughly $170 more every month for the same loan amount, purely because of the rate and the shorter term.
The longer new-boat term has a trade-off: you pay more interest in total over 15 years than over 10, even at the lower rate. Run your own numbers on our boat loan calculator before you decide, because the right answer depends on whether a low monthly payment or a low total cost matters more to you.
A smaller example shows the same pattern. A $40,000 new boat at 7% over 12 years costs about $411 a month. The same $40,000 as a used boat at 9.5% over 8 years costs about $596 a month. The used boat is cheaper to buy, but the loan is dearer to carry.
When is a used boat still the smarter choice to finance?
Financing is only one side of the deal. A used boat often costs far less to buy, and that lower price can outweigh the higher loan cost. A boat that is two to five years old is often the sweet spot: it has already lost its steepest early depreciation, it is still young enough for most lenders, and it may still carry some warranty.
A used boat also makes sense when you can put down a larger deposit, which offsets the higher rate, or when you plan to keep the boat for many years and the monthly payment still fits your budget. Our used boat loan calculator shows what the payment would be before you commit. For the wider buying decision, compare the two options in our new vs used boat guide.
How to make a used boat loan easier to get
If your heart is set on a used boat, there are practical ways to smooth the financing. Get a marine survey done before you apply, so the lender sees a clean report. Gather the boat’s service records and maintenance history. Offer a larger deposit to bring the loan-to-value ratio down. Keep the loan term as short as you can afford, and get pre-approved before you start shopping so you know your budget and your rate in advance.
A strong credit score helps in both cases, but it matters more on a used boat, where the lender is already taking extra risk. Even a small improvement in your score can move you into a better rate band.
The bottom line
A new boat is easier to finance: lower rates, longer terms, no survey and a faster approval. A used boat costs more to finance but often far less to buy, so the cheaper monthly payment does not always mean the cheaper deal. Compare the total cost of both options, check what you can actually borrow, and choose the boat that fits your budget rather than the one with the easiest paperwork.
Do banks prefer financing new or used boats?
Banks prefer new boats because the value is certain, the boat has a warranty and there is no wear to assess. Used boats are still financed, but usually at higher rates, with shorter terms and a marine survey requirement.
How old can a boat be to finance?
Most marine lenders cap the boat’s age at the end of the loan, often around 20 years, and some refuse boats older than 10 to 15 years. The exact limit varies by lender, so check before you fall in love with an older boat.
Can I get a 20-year loan on a used boat?
Very rarely. Twenty-year terms are generally reserved for new or nearly new boats. Used boats usually qualify for 10 to 15 years at most, and older boats for less.
Do used boat loans have higher interest rates?
Yes, typically one to two percentage points higher than a comparable new-boat loan. The lender charges more because an older boat carries greater risk of falling value and hidden repair costs.

Michael Carter is a financial research writer specializing in vehicle financing, loan calculations, interest rates, and consumer budgeting. He creates practical, easy-to-understand resources that help readers make more informed financing decisions.