Is Boat Loan Interest Tax Deductible?
Is boat loan interest tax deductible? For many buyers, yes. If your boat meets the IRS definition of a second home and your loan is secured by the boat, the interest you pay can qualify for the home mortgage interest deduction, just like the interest on a vacation cabin. But the rules are strict, and not every boat or loan passes the test.
Most buyers finance their boat without ever thinking about taxes. If you are still shopping around, read our guide on how to finance a boat first. But if your vessel has a real cabin, the deduction can be worth thousands of dollars over the life of the loan. This guide walks through the exact conditions, the dollar limits, and a new bill in Congress that could make the tax break simpler.
The short answer
A boat is not automatically a tax write-off. Interest on a personal-use car loan is never deductible, and most boat loans work the same way. The exception exists because the tax code treats a qualifying boat exactly like a second home. That puts the interest on the same footing as mortgage interest, as long as the boat and the loan each pass a short list of tests. A small open fishing boat will not pass. A cabin cruiser with a berth, a galley, and a head often will.
When is boat loan interest tax deductible?
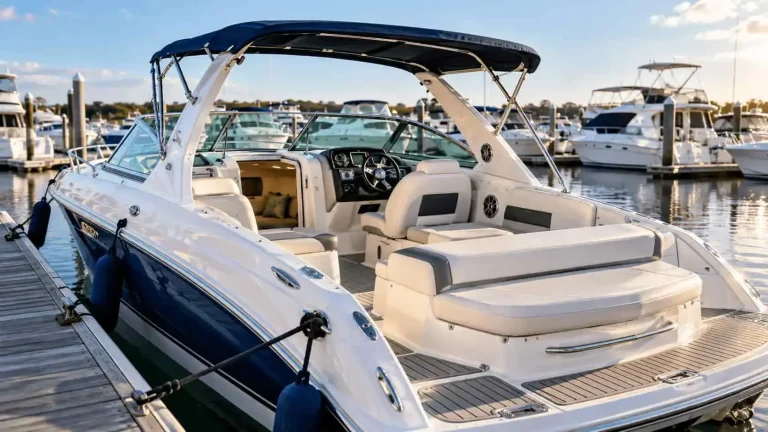
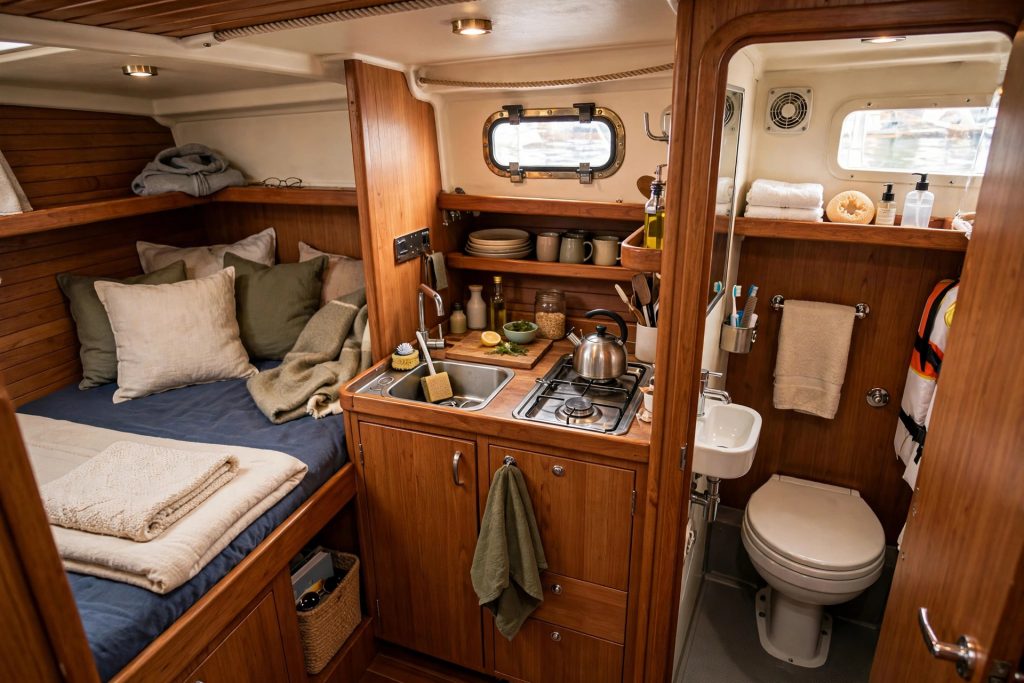
The IRS says a boat counts as a second home when it has basic living accommodations: sleeping space, toilet facilities, and cooking facilities. In boating terms, that means a sleeping berth, an installed head, and a galley. A cooler and a camping stove do not count. If your boat clears all three tests, the interest on a secured loan used to buy it can be deducted.
There is one more condition that trips people up. You can only claim the mortgage interest deduction for one second home in addition to your primary residence. If you already deduct interest on a lake house, you cannot stack a boat on top of it.
What your loan has to look like
Qualifying the boat is only half the job. The loan itself has to fit the rules too:
- It must be secured by the boat. Most marine loans are secured, meaning the lender holds the boat as collateral. An unsecured personal loan you happen to spend on a boat does not qualify.
- You must itemize deductions. The interest is claimed on Form 1040, Schedule A. If the standard deduction gives you a bigger total write-off, the boat interest adds nothing on top.
- The debt must be acquisition debt used to buy, build, or substantially improve the boat.
- Watch the ceiling. Interest is deductible on up to $750,000 of total home debt, counting your primary residence and the second home together ($375,000 if you are married filing separately).
Paperwork matters. If your lender sends you Form 1098 showing the interest you paid, enter the amount on line 10 of Schedule A. If you never got a 1098, you can still claim it: enter the amount on line 11 along with the lender’s name, address, and tax identification number.
What the deduction is worth: a quick example
Take a $120,000 boat bought with 20 percent down, so $96,000 is financed at 8 percent APR over 15 years. The monthly payment comes to about $917. In the first year, roughly $7,550 of those payments is interest. For a borrower in the 22 percent tax bracket, the deduction cuts the tax bill by about $1,660 that year.
Run your own numbers before you file. Our boat loan calculator by loan amount shows what the payment looks like, and the boat loan APR calculator shows how much of it is interest in the early years, which is exactly the part that can be deductible.
A new bill could make it even simpler
In January 2026, Rep. Nancy Mace (R-SC) introduced H.R.7222, the No Tax on Boat Loan Interest Act of 2026, and it was referred to the House Committee on Ways and Means. The bill would extend the existing above-the-line interest deduction for American-made motor vehicles to qualifying recreational boats assembled in the United States.
Under the proposal, buyers could deduct up to $10,000 per year in loan interest through 2028, with the benefit phasing out for taxpayers above $100,000 in modified adjusted gross income ($200,000 for joint filers). The boat must be new to the buyer, classified as a recreational vessel and a motorboat, and the buyer would report the vessel’s hull identification number on the tax return.
The bill is backed by the National Marine Manufacturers Association, the Marine Retailers Association of the Americas, and BoatUS. It has not become law, so treat it as a bill to watch rather than a break you can claim on this year’s return.
What if you own a boat in the UK?
There is no equivalent deduction for personal boat finance in the UK. Interest on a personal loan or marine mortgage taken out for private use is not deductible against personal income tax. If the boat is used for a genuine business, such as a charter fleet, the interest may count as a business expense. Liveaboard financing has its own quirks as well; see our guide on how to finance a liveaboard boat.
Your pre-tax-season checklist
- Confirm your loan is secured by the boat itself.
- Confirm the boat has a berth, a head, and a galley.
- Keep your Form 1098 or year-end interest statement.
- Check whether itemizing actually beats the standard deduction for you.
- Talk to a tax professional about your situation. This article explains the general rules, but it is not tax advice.
So, is boat loan interest tax deductible? It is, when the boat qualifies as a second home and the loan is secured and used to buy it. Check the conditions before you count on the savings, keep your paperwork in order, and you may shave real money off the cost of boat ownership.

Michael Carter is a financial research writer specializing in vehicle financing, loan calculations, interest rates, and consumer budgeting. He creates practical, easy-to-understand resources that help readers make more informed financing decisions.