Can You Buy a Boat Through Your Business?
Yes, you can buy a boat through your business, if the boat has a genuine business purpose. The business can pay for it, finance it, or lease it, and the costs that relate to business use may be treated differently from personal costs. But personal use of a business-owned boat can create tax problems, and the tax treatment depends on how much the boat is actually used for business. Talk to a tax professional before you buy, because the rules are detailed and they change.
This is not a way to make a personal boat tax deductible. The tax authorities look at actual use, not at what the purchase is called. A charter boat that earns money most weekends is a very different case from a boat that is used for family trips with one client meeting a year. Records decide which case you are in, and records kept after the fact are worth far less than records kept as you go.
What buying through your business actually means
When a business buys a boat, the business is the buyer and the owner. The title, the loan, and the insurance are in the business name, not in your personal name. The business pays for the boat, and the business claims the costs that relate to its business use.
You as an individual do not own the boat, even if you own the business. That distinction matters for tax, for liability, and for what happens when you sell. It also matters for finance, because the lender will look at the business as well as at you.
Business uses that make sense
The strongest cases are businesses built around boats. Charter and tour operations, fishing guides, water taxis, rental fleets, workboats for a marine business, survey work, and dive operations all have a clear business reason to own a boat. The boat earns money directly, and its costs are part of running the business.
Client entertainment is a harder case. Taking clients out on a boat can be a real business activity, but it is also easy to exaggerate. If the boat is used for clients a few times a year and for family trips the rest of the time, the business portion is small, and only that portion can be treated as a business cost.
Personal use with occasional business use is the weakest case. If the business reason is invented after the purchase, or if the boat is really a family boat with a business label on it, the tax treatment will not survive a close look. Be honest about the split from the start.
How business boat financing works
A business can finance a boat in several ways. An equipment loan secured by the boat is the most common route. A general business loan is another option. A lease is a third, and it suits businesses that want to upgrade regularly or that do not want to own the boat at the end of the term.
The lender will check the business first: its revenue, how long it has traded, and its existing debts. For a small business, the lender will usually also check the owner’s personal credit, and a personal guarantee is common. A personal guarantee means you are personally responsible if the business cannot pay, so the protection of a business structure does not extend to the loan itself.
Newer businesses may be asked for a larger deposit or a shorter term, because the lender has less history to judge. If you are self-employed, our guide to getting a boat loan when self-employed explains what lenders look at in that situation, and much of it applies to a small business application too.
Before you apply, read the boat loan requirements so you know what documents to prepare. Business applications usually need more paperwork than personal ones, including business accounts and formation documents.
LLC, sole proprietorship, or corporation
The business structure changes how the business is run, but it does not by itself change the tax question. Actual use still decides that.
A sole proprietorship is the simplest structure. There is no legal separation between you and the business, so the boat is effectively yours and the business’s at the same time. That simplicity comes with personal exposure if something goes wrong.
A limited liability company, or LLC, separates the business from your personal assets in general terms. That separation is useful, but it does not protect you against a loan you have personally guaranteed, and it does not turn personal use into business use.
A corporation is more formal, with more paperwork and more rules. It suits larger operations better than a single boat.
Which structure fits your situation is a question for a tax or legal professional, not for a boat dealer or a lender. Get that advice before you buy, not after.
The tax side, in general terms
For the portion of the boat’s use that is genuinely for business, costs such as loan interest, depreciation, fuel, maintenance, and berthing may be deductible, in proportion to the business use. If the boat is used for business half the time, roughly half the costs relate to business, and the other half does not.
The personal use portion is not deductible. Claiming the full cost of a boat that is mostly used privately is the single most common mistake in this area, and it is the one most likely to cause trouble.
Rules differ by country and they change over time, and this article is not tax advice. Our guide to whether boat loan interest is tax deductible covers the personal side of the same question. For a business purchase, a tax professional who knows your situation is the right source for the final answer.
Personal use: where people get into trouble
Most problems in this area come from the same few habits. Using a business boat mostly for family trips and claiming the full costs. Keeping no records, so there is no way to prove the business use when it is questioned. Claiming the whole boat when only part of the use is business. Forgetting that personal use of a company asset can itself have a tax effect.
The fix is simple and it starts on day one. Keep a log of every trip: the date, the purpose, who was aboard, and the business reason. Keep business and personal money in separate accounts. Split the costs by the same proportion as the use, and be honest about that proportion. A log kept as you go is believable. A log reconstructed a year later is not.
Insurance and liability
The insurance policy must name the business as the owner and must cover the business use. Charter use needs different cover from private use, and a private policy may not pay out if the boat was being used commercially when something happened. Check who is allowed to operate the boat, and make sure every operator is covered.
Liability follows the same logic as the rest of this article. A business structure can limit your personal exposure in general terms, but it does not remove it where you have personally guaranteed a loan or where you were personally at fault. Keep the insurance current and matched to the real use of the boat.
Steps to buy a boat through your business
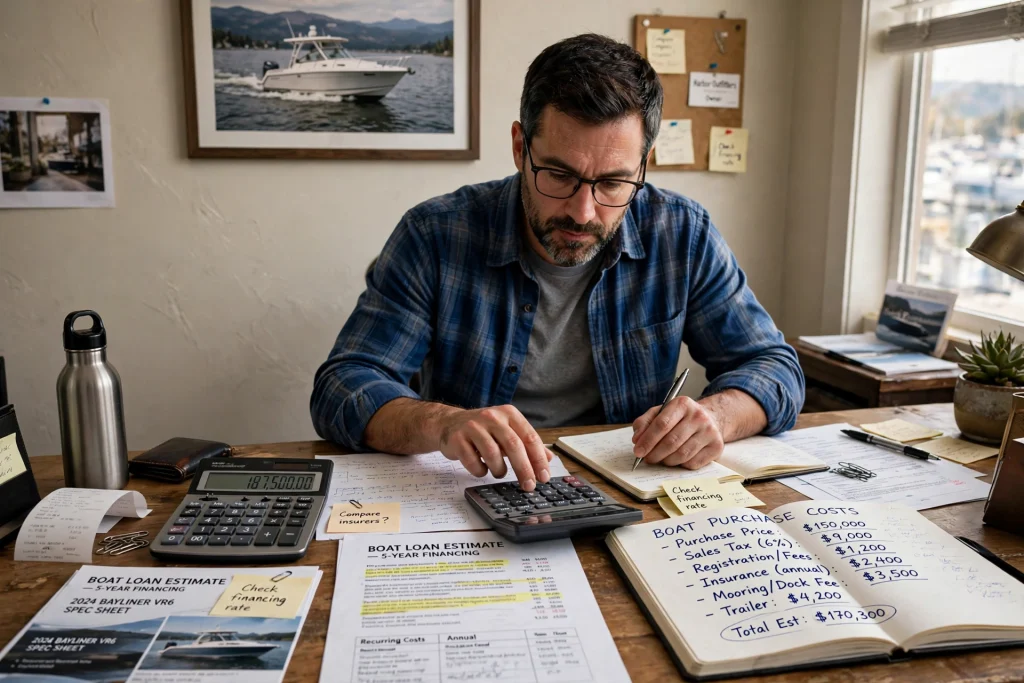
Work through these steps in order. First, define the business purpose in writing. What will the boat do for the business, and how often? Second, talk to a tax professional about the structure, the record keeping, and the likely tax treatment. Third, confirm or choose the business structure. Fourth, get lender quotes and compare a business loan against a personal loan on the same numbers.
Fifth, survey the boat and check the title before you commit. Our boat survey guide explains what a survey covers and why it matters, especially for a used boat. Sixth, arrange insurance in the business name, matched to the business use. Seventh, buy with the business as the buyer, keep every receipt, and start the use log on the first day.
Before you set a budget, run the numbers through the boat affordability calculator and the boat loan calculator on our homepage, so the purchase fits the business as well as your plans.
Mistakes to avoid
Buying first and inventing a business reason later is the biggest mistake. Mixing personal and business money in one account is the second. Keeping no logbook is the third. Assuming the whole cost is deductible is the fourth. Ignoring the personal guarantee in the loan is the fifth. Forgetting that selling the boat later can itself have tax effects is the sixth.
A boat bought through your business can be a smart move when the business use is real, the records are kept, and the finance fits. When the business use is thin and the records are missing, it is a personal boat with extra paperwork and extra risk. The difference is not the structure you choose. It is the use, the records, and the honesty about both.

Michael Carter is a financial research writer specializing in vehicle financing, loan calculations, interest rates, and consumer budgeting. He creates practical, easy-to-understand resources that help readers make more informed financing decisions.