How long can you finance a 60k boat?
A $60,000 boat can typically be financed for 10 to 15 years. Borrowers with strong credit (around 700 and up) financing a new or nearly new boat can sometimes stretch to 20 years. Shorter terms mean higher monthly payments but far less total interest over the life of the loan.
What loan terms can you get on a $60,000 boat?
Most lenders quote boat loan terms of 60, 84, 120, 180 or 240 months — 5, 7, 10, 15 and 20 years — and where you land depends heavily on the loan amount. Lenders typically offer 10 to 15 years on loans between $25,000 and $100,000, which puts a $60,000 purchase squarely in that band. A 20-year term is possible, but it is reserved for the strongest credit profiles and the newest boats. For the bigger picture, see the absolute ceiling on boat loan terms.
What does a $60k boat cost per month at each term?
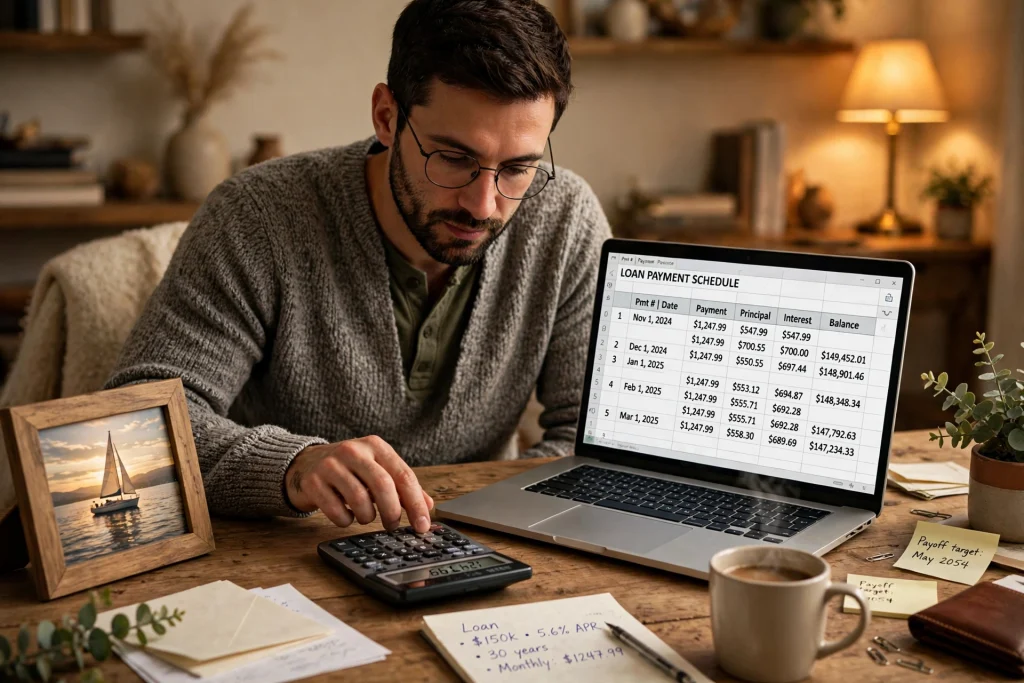
Assuming 7.5% APR — right in the middle of the 6.9% to 7.8% range that counts as strong for 2026 — here is what a $60,000 loan costs at the three realistic terms:
| Loan term | Monthly payment | Total interest |
|---|---|---|
| 10 years (120 months) | about $712 | about $25,500 |
| 15 years (180 months) | about $556 | about $40,100 |
| 20 years (240 months) | about $483 | about $56,000 |
The 20-year option saves roughly $230 a month versus the 10-year term but costs more than twice the total interest. Note that lenders often price 15- and 20-year terms a touch higher than 10-year terms, so your real rate may sit slightly above these examples — check what counts as a good rate for your credit tier, then run your own numbers on the main boat loan calculator.
What decides whether you qualify for 10, 15 or 20 years?
Your credit score. Borrowers around 700 and up qualify for the longest terms and lowest rates; weaker credit usually means shorter terms, higher rates, or both.
The boat’s age. New or nearly new boats qualify for the longest terms — up to 20 years. Used boats generally top out around 15 years, and only when the boat is under roughly 10 years old.
Secured vs unsecured. A secured marine loan — where the boat itself is the collateral — unlocks the 10- to 20-year range. Unsecured personal loans used for boats typically max out around 7 years.
Your down payment. Putting down 20% instead of 10% will not directly extend your term, but it can shave a quarter to half a point off your rate by lowering the loan-to-value ratio, which makes every term cheaper.
Is stretching to 20 years smart on a $60k loan?
The math is the same trap as on any long loan: a 20-year term on $60,000 at 7.5% costs about $56,000 in interest — nearly as much as the loan itself. If the 15-year payment feels too high, a larger down payment is usually a smarter move than a longer term. Model the trade-off yourself with the 20-year boat loan calculator before you sign.
Can you get a 20-year loan on a $60k boat?
Yes, but it is not the norm. Most lenders reserve 20-year terms for larger balances and borrowers with credit around 700 and up financing new boats. Expect 10 to 15 years as the standard offer on a $60,000 purchase.
What is the shortest term available on a $60k boat loan?
Three years is a common minimum for secured marine loans. Shorter terms mean higher monthly payments but far less total interest over the life of the loan.
Will a used $60k boat get the same terms as a new one?
Usually not. New boats qualify for the longest terms — up to 20 years — while used boats generally top out around 15 years, and only when the boat is under roughly 10 years old.
Can I shorten my boat loan term later?
Yes. You can refinance into a shorter term or make extra payments toward the principal. Check your loan agreement first for any prepayment penalty.

Michael Carter is a financial research writer specializing in vehicle financing, loan calculations, interest rates, and consumer budgeting. He creates practical, easy-to-understand resources that help readers make more informed financing decisions.